TAKAFUL FOR YOU & YOUR FAMILY

Understand Your Cover.
Plan for Your Family.

Already have takaful, or thinking about your first plan? Let's talk about what you need, what you already have and a budget you're comfortable with.
A FEW THINGS WORTH THINKING ABOUT

Life Can Change. The Bills Keep Coming.

START WITH WHERE YOU ARE TODAY

Life Changes. Your Needs Do Too.

Starting work, raising a family or buying a home? Let's understand your situation before looking at plans.

Ask Faizal
Individuals

New to takaful? Let's start with your commitments and budget.
Breadwinners

Does someone depend on your income? Let's talk about the support they may need.
Young families

Plan ahead for your family's healthcare and your children's education.
Homeowners

Review your outstanding home financing and any cover you already have.

WHAT WOULD YOU LIKE TO PREPARE FOR?

Start with what matters to you

Choose the concern that's on your mind. Not sure where to start? You can ask Faizal first.

8solutions to explore
01
3D illustration for Income Protection

Income Protection

If a covered event stops your income, your family's bills still need paying. Let's talk about a fund that could help them manage.

“Your income may stop. Your family's needs don't.”
What this could look like

If a main earner dies or experiences a covered disability, groceries, rent, school fees and monthly bills still need paying.
How it helps & what to check +
WHAT TO KEEP IN MIND

Start with your family's monthly spending, how long they may need support and any cover you already have. These help you work out an amount that makes sense.

HOW IT CAN HELP

What could it help with?

A benefit payout may help beneficiaries cover household expenses and important commitments for the period you've planned for, subject to the certificate terms.

IF THERE ISN'T A PLAN IN PLACE

What could this mean for your family?

You

Money worries may grow when your health or ability to work is affected.

Your partner

Your partner may have to cover household expenses on one income while caring for the family.

Your children

Everyday spending, activities or education plans may need to be reduced or put on hold.

Heirs / guardians

Savings or estate assets may have to cover living costs and ongoing commitments.

THINK OF IT THIS WAY

Like a water storage tank, it gives your family a temporary supply when the main flow stops.

ILLUSTRATIVE EXAMPLE

Amir supports his wife and two children on a household budget of RM4,000 a month. If a covered event happens, an eligible payout could give them a temporary fund while they adjust their finances. This is a fictional example.

Who might find this useful?

Breadwinners, parents and anyone with people who depend on them financially.

What should we talk through?

How much does your family spend each month? How long might they need support, and what cover do you already have?

Explore this type of cover (BM) Ask Faizal on WhatsApp
02
3D illustration for Medical Card

Medical Card

Get help with eligible hospital bills. Let's also check the limits and what you may still need to pay yourself.

“When you're in hospital, it helps to know where you stand with the bill.”
What this could look like

A hospital bill can arrive unexpectedly. Cover from your employer may have limits, exclude certain treatments or end when you leave your job.
How it helps & what to check +
WHAT TO KEEP IN MIND

An annual limit doesn't tell the whole story. Check the deductible, co-takaful, room limit, waiting periods and exclusions too. The deductible and co-takaful affect what you pay yourself.

HOW IT CAN HELP

What could it help with?

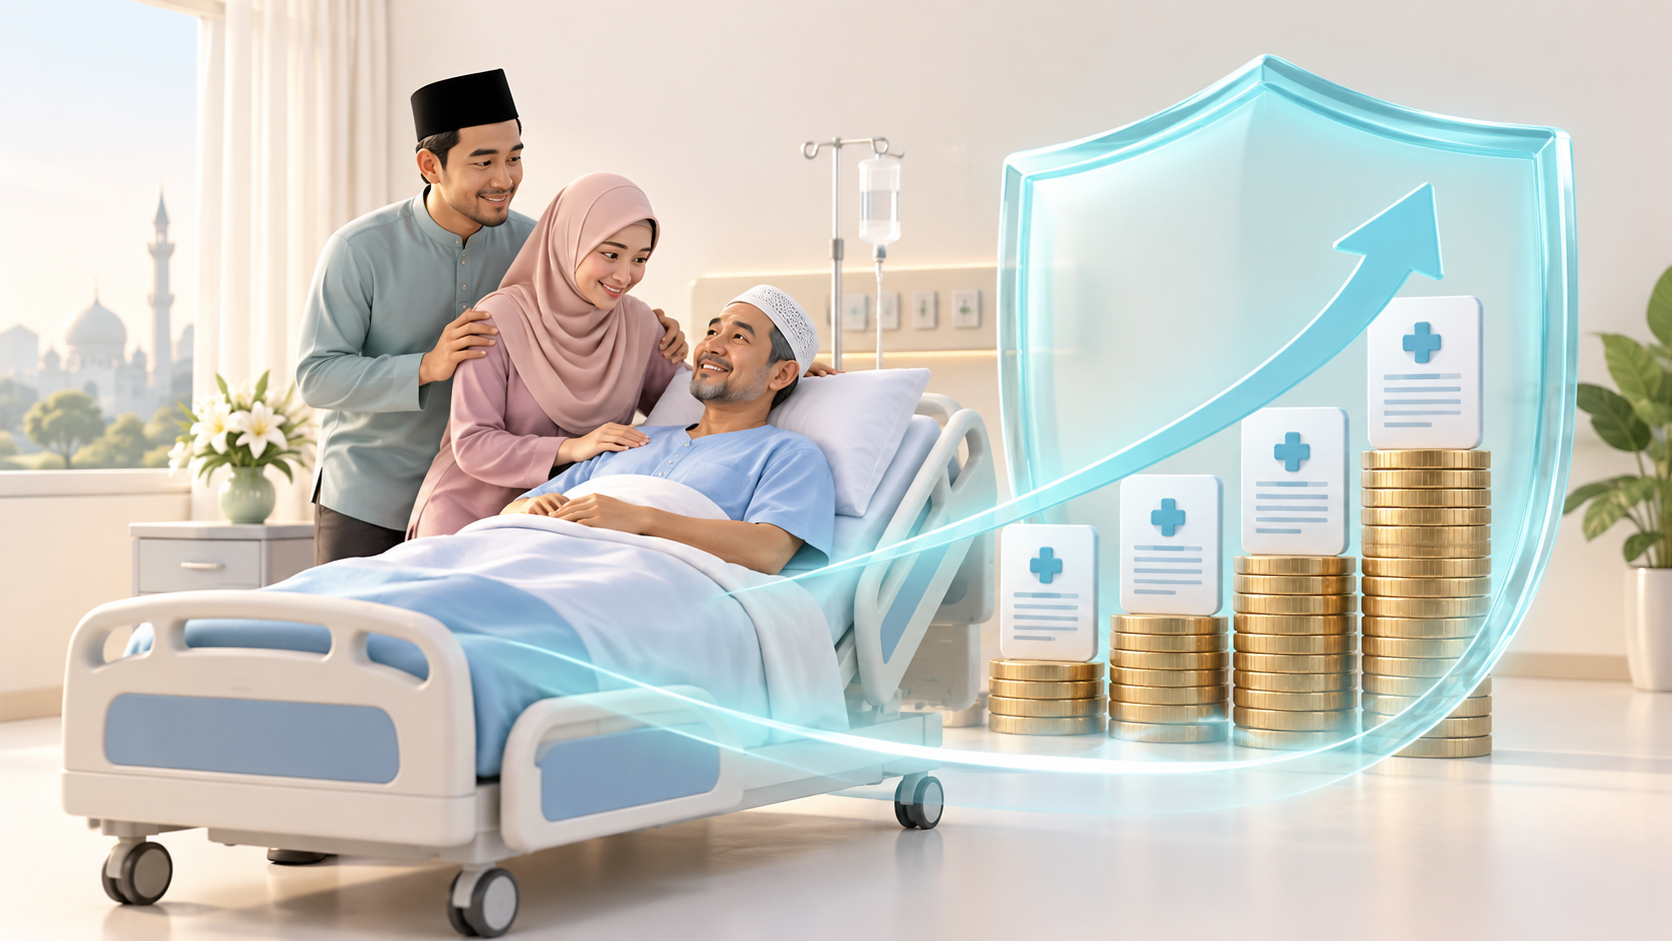
It can help pay eligible hospital and treatment costs, subject to annual limits, your share of the bill, exclusions and certificate terms.

IF THERE ISN'T A PLAN IN PLACE

What could this mean for your family?

You

You may need to use your savings quickly or postpone some treatment options because of the cost.

Your partner

Your partner may need to help pay the bills, take leave or arrange care during treatment.

Your children

Household spending, daily routines and education savings may be affected when money goes towards treatment.

Heirs / guardians

Heirs or guardians may have to handle paperwork, unpaid bills or an estate with fewer assets.

THINK OF IT THIS WAY

Like an umbrella in the rain, it offers cover within its limits. You still need to know how far that cover reaches.

ILLUSTRATIVE EXAMPLE

Aina is admitted for appendicitis. Her medical card may help pay eligible treatment costs, but she still needs to check the deductible, co-takaful and exclusions. This is a fictional example.

Who might find this useful?

Individuals and families who want cover for eligible hospital treatment costs.

What should we talk through?

What annual limit makes sense? What are the terms for your preferred room and hospital, and how much might you pay yourself?

Explore this type of cover (BM) Ask Faizal on WhatsApp
03
3D illustration for Critical Illness Protection

Critical Illness Protection

Hospital bills are one thing. Household bills while you recover are another. This cover may provide cash if a diagnosis meets the plan's terms.

“While you recover, the household bills keep coming.”
What this could look like

A medical card may help with eligible hospital bills. Home instalments, food, childcare and lost income during recovery still need planning for.
How it helps & what to check +
WHAT TO KEEP IN MIND

Medical cover usually pays eligible treatment costs. A critical illness benefit may provide cash when the diagnosis meets the claim definitions and conditions.

HOW IT CAN HELP

What could it help with?

It may pay a lump sum if the diagnosis meets the definitions and severity level covered by the plan. You could use it for living costs, recovery or replacing income.

IF THERE ISN'T A PLAN IN PLACE

What could this mean for your family?

You

Recovery may feel harder when your income drops but the bills keep coming.

Your partner

Your partner may have to care for you and become the main earner at the same time.

Your children

Your children's routines, care arrangements or education plans may change while the family adjusts its budget.

Heirs / guardians

Family savings or estate assets may be used earlier than planned for living costs and recovery.

THINK OF IT THIS WAY

Think of it as a financial bridge between diagnosis and being able to return to work.

ILLUSTRATIVE EXAMPLE

Siti needs six months off after cancer treatment. If her claim qualifies, a critical illness payout could help with home commitments and family expenses while her income is lower. This is a fictional example.

Who might find this useful?

Working adults, breadwinners and anyone who wants an extra financial buffer during treatment and recovery.

What should we talk through?

How many months of income might you need to replace? Which illnesses and severity levels are covered, and what conditions must a claim meet?

Explore this type of cover (BM) Ask Faizal on WhatsApp
04
3D illustration for Debt Protection

Debt Protection

Explore a fund that could reduce or settle selected debts if a covered event happens.

“It's worth planning for the commitments your family may have to manage.”
What this could look like

Outstanding personal financing, car financing and other debts may still affect the estate and family if the breadwinner dies or becomes disabled.
How it helps & what to check +
WHAT TO KEEP IN MIND

Debt doesn't automatically disappear when someone dies. What happens next depends on the contract, any joint borrowers or guarantors, and the estate process.

HOW IT CAN HELP

What could it help with?

You can compare selected outstanding debts with a suitable cover amount. An eligible payout may help reduce or settle those commitments.

IF THERE ISN'T A PLAN IN PLACE

What could this mean for your family?

You

Debt payments may leave less room in your budget when your income or health is affected.

Your partner

A joint borrower or guarantor may need to keep paying under the financing agreement.

Your children

Family spending may have to be cut if much of the income goes towards debt payments.

Heirs / guardians

Handling the estate may become more complicated. Assets may need to be used to settle valid debt claims.

THINK OF IT THIS WAY

Think of a heavy anchor on a boat. Planning ahead may help reduce the weight your family has to manage.

ILLUSTRATIVE EXAMPLE

Farid has RM120,000 left on personal and car financing. Cover planned around that balance could help his family manage the debt if a covered event happens. This is a fictional example.

Who might find this useful?

People with personal, car or business financing, or other debt commitments.

What should we talk through?

Which debts do you want to cover? What is the actual balance, and do they already have protection?

Explore this type of cover (BM) Ask Faizal on WhatsApp
05
3D illustration for Home Financing Protection / MRTT

Home Financing Protection / MRTT

Review the cover for your outstanding home financing so you know what support may be available if a covered event happens.

“A family home also comes with instalments worth planning for.”
What this could look like

If a borrower dies or becomes totally and permanently disabled, their partner may have to keep paying the home instalments on one income.
How it helps & what to check +
WHAT TO KEEP IN MIND

MRTT cover usually reduces over time. Compare it with the actual outstanding financing from time to time.

HOW IT CAN HELP

What could it help with?

It typically provides reducing cover over the financing term. An eligible benefit may help settle the outstanding home financing if a covered event happens.

IF THERE ISN'T A PLAN IN PLACE

What could this mean for your family?

You

If your partner can no longer contribute, you may have to pay the home instalments on your own.

Your partner

Your partner may face difficult choices about keeping, refinancing or selling the home.

Your children

Your children's home, school arrangements and family routines may be disrupted.

Heirs / guardians

Outstanding home financing may need to be addressed before the estate process can be completed.

THINK OF IT THIS WAY

Think of an extra layer of cover for the home financing if something happens to the main borrower.

ILLUSTRATIVE EXAMPLE

Hakim and Nadia buy a home with 30-year financing. If Hakim, the main borrower, experiences a covered event, suitable MRTT may help reduce or settle the outstanding financing. This is a fictional example.

Who might find this useful?

Homebuyers and homeowners with outstanding home financing.

What should we talk through?

Do the MRTT amount and term match your financing? Who is covered, and which events qualify?

Explore this type of cover (BM) Ask Faizal on WhatsApp
06
3D illustration for Retirement Planning

Retirement Planning

Your salary may stop, but the bills won't. Let's look at your retirement savings goal and what you already have.

“When your salary stops, what will cover your monthly spending?”
What this could look like

Food, housing, healthcare and day-to-day spending continue after retirement. Inflation may also push these costs up.
How it helps & what to check +
WHAT TO KEEP IN MIND

Starting earlier gives you more time to save regularly. Remember to allow for inflation when estimating future expenses.

HOW IT CAN HELP

What could it help with?

It helps you set a retirement savings target and work towards it with regular savings that suit your timeline, budget and risk tolerance.

IF THERE ISN'T A PLAN IN PLACE

What could this mean for your family?

You

You may need to work longer, spend less or rely on others for support.

Your partner

Shared savings may not be enough to cover both partners' needs.

Your children

Your children may need to help with your expenses while managing their own families and commitments.

Heirs / guardians

Assets you hoped to leave behind may have to cover retirement living costs.

THINK OF IT THIS WAY

Like growing a tree, small regular contributions need time before they can provide shade.

ILLUSTRATIVE EXAMPLE

Lina is 35 and wants to retire at 60. By estimating her monthly spending, she can work out a savings gap and start putting money aside earlier. This is a fictional example.

Who might find this useful?

People who want to rely less on their children or employment income in retirement.

What should we talk through?

When would you like to retire? What might you spend each month, and what retirement savings do you already have?

Explore this type of cover (BM) Ask Faizal on WhatsApp
07
3D illustration for Children's Education Fund

Children's Education Fund

Children grow up quickly, and education needs planning too. Let's set a savings goal based on your child's age and your budget.

“When your child is ready for university, will the fund be ready too?”
What this could look like

Tuition, accommodation and living costs can be harder to manage if saving only starts when a child is about to enter college or university.
How it helps & what to check +
WHAT TO KEEP IN MIND

The date matters. Your monthly savings depend on the target cost, current savings, inflation and the time left.

HOW IT CAN HELP

What could it help with?

It helps you set an education savings goal and put money aside regularly, based on the amount needed, time available and your family's budget.

IF THERE ISN'T A PLAN IN PLACE

What could this mean for your family?

You

You may have to use other savings, take on debt or work longer to cover the cost.

Your partner

Your partner may need to adjust the family budget and other goals to find the money at short notice.

Your children

Your child may need to choose a lower-cost course, delay studying or rely on a loan.

Heirs / guardians

Guardians or heirs may find it harder to keep the education plan on track if the main contributor is no longer around.

THINK OF IT THIS WAY

Think of building a staircase, one step at a time, towards your child's next stage of education.

ILLUSTRATIVE EXAMPLE

Roslan's child is five years old and is expected to start university in 13 years. Roslan can set a fund target, save monthly and review progress along the way. This is a fictional example.

Who might find this useful?

Parents or guardians who want to plan ahead for a child's education costs.

What should we talk through?

When will the money be needed? What might education cost, and how much can you keep saving each month?

Explore this type of cover (BM) Ask Faizal on WhatsApp
08
3D illustration for Savings Planning

Savings Planning

What are you saving for, how much do you need and when? Let's start with a clear goal and an amount you can keep putting aside.

“Give your goal an amount and a date. Then work out the steps.”
What this could look like

Savings can get spent on other things when there's no clear goal, contribution schedule or separate account for it.

How it helps & what to check +
WHAT TO KEEP IN MIND

Your goal, timeline and current savings help determine how much to put aside. Future values and returns should not be treated as guaranteed.

HOW IT CAN HELP

What could it help with?

It helps you save towards goals such as a home deposit, wedding or future capital, with the features and risks of the chosen plan in mind.

IF THERE ISN'T A PLAN IN PLACE

What could this mean for your family?

You

Your goal may be delayed, or you may need to borrow when the money is needed.

Your partner

Shared plans, such as a home or wedding, may need extra compromises.

Your children

Your children's future options and needs may be harder to support if the family fund falls short.

Heirs / guardians

The emergency fund or assets available to your family may be smaller than planned.

THINK OF IT THIS WAY

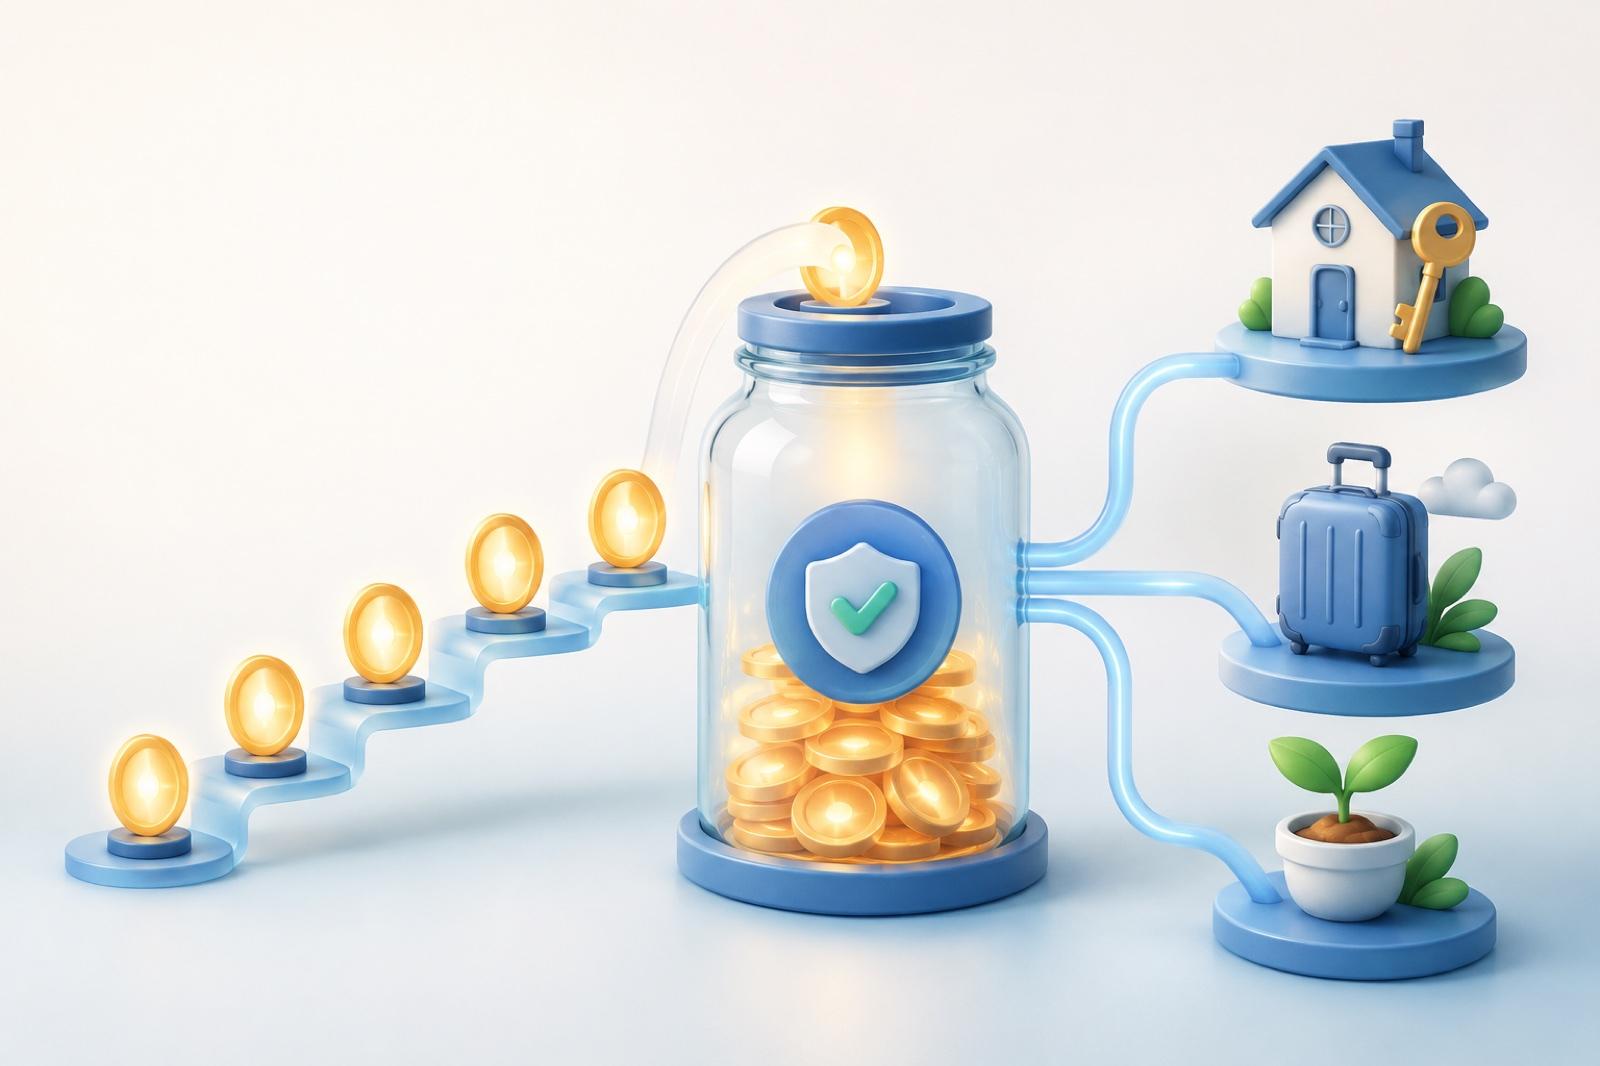
Think of filling a jar a little at a time. Regular saving breaks a larger goal into smaller steps.

ILLUSTRATIVE EXAMPLE

Maya wants RM30,000 for a home deposit in five years. A savings plan helps her work out a monthly amount and see whether the goal is realistic. This is a fictional example.

Who might find this useful?

People with medium- or long-term financial goals who want more structure in their saving habits.

What should we talk through?

What are you saving for, and when will you need it? How much can you afford, and what happens if contributions stop early?

Explore this type of cover (BM) Ask Faizal on WhatsApp

These are general planning principles. The examples are fictional and help explain the ideas; they do not predict outcomes or promise payouts. Actual cover depends on the product, certificate terms, covered event and eligibility assessment.

SIMPLE BUDGET CALCULATOR

What Monthly Budget Feels Comfortable?

Adjust your age and budget to get a rough picture of the commitment. This simple calculation isn't a quote or confirmation of eligibility.

TRY THE NUMBERS

Monthly contribution budget

Choose an amount you feel you could keep paying. This figure doesn't tell you what benefits you would receive.
Illustrative total contributions to age 60RM 75,000RM 250 × 12 × 25 years. This is the total contribution amount for comparing budget commitments. It is not a benefit amount or investment return.
Explore the full calculators & summary →
Karikatur Faizal Ahmad, consultant takaful

Meet Faizal Ahmad

Want to understand your cover but not sure where to start? Tell me what you’d like to know. We’ll start with your questions, then discuss the information needed to understand the options relevant to you.

Start with
your questions
Understand
the information
Discuss
relevant options
Message Faizal
“You don't need to know every takaful term to ask a question. Let's take it one step at a time.”
Faizal AhmadTakaful Consultant

COMMON QUESTIONS

You Might Be Wondering…

These answers are a general guide. For your own plan, we need to check the details and certificate terms.

What should I do if I need to go into hospital?+

The process depends on the hospital, panel arrangements, guarantee letter and certificate terms. If circumstances allow, contact your operator or consultant beforehand.

I already have a plan. Can I add or change my cover?+

That depends on the product, your age, health, underwriting and current terms. Review your existing cover before making changes.

Are all illnesses and treatments covered?+

Not always. Every certificate has its own benefit definitions, exclusions, waiting periods, limits and claim conditions.

How do I work out how much cover I need?+

Start with your family's spending, debts, dependants and existing cover. Then consider how long support may be needed and a budget you can keep paying.

START WITH ONE MESSAGE

What's On Your Mind?

Fill in the details below to prepare a WhatsApp message to Faizal. You can review it before sending. No payment or purchase takes place here.
These details fill a WhatsApp draft when you press the button. This page doesn't store them.
Chat with Faizal on WhatsApp
Faizal Ahmad | Takaful Consultation for You & Your Family