An emergency fund isn't something everyone has
BNM reported that only 58% of Malaysians actively save for the future, and many cannot cover a RM1,000 emergency.
Bank Negara Malaysia, 2 Oct 2025 ↗TAKAFUL FOR YOU & YOUR FAMILY
Already have takaful, or thinking about your first plan? Let's talk about what you need, what you already have and a budget you're comfortable with.
Understand which hospital bills may be covered and what you may still need to pay.
Talk through the financial support you want to leave for your loved ones.
Explore a cash buffer for everyday expenses during treatment and recovery.
Start planning for your savings goals and your children's education at a pace you can afford.
A FEW THINGS WORTH THINKING ABOUT
BNM reported that only 58% of Malaysians actively save for the future, and many cannot cover a RM1,000 emergency.
Bank Negara Malaysia, 2 Oct 2025 ↗Total MHIT claims costs rose 73% between 2021–2023, compared with premium growth of 21% over the same period.
BNM Annual Report 2024 ↗Household out-of-pocket spending accounted for 36% of Malaysia's total health expenditure in 2023.
Malaysia National Health Accounts 2024 ↗Average monthly household consumption expenditure rose from RM5,150 in 2022 to RM5,566 in 2024.
DOSM, Household Expenditure Survey 2024 ↗Four main groups, housing, food, restaurants and transport, made up 67.2% of household consumption expenditure in 2024.
DOSM, Household Expenditure Survey 2024 ↗In 2024, 21.8% of Malaysian households received a gross monthly income below RM4,000.
DOSM, Household Income Survey 2024 ↗Belanjawanku 2024/2025 estimates that a single older person in the Klang Valley needs RM2,690 a month for a reasonable standard of living.
EPF, Belanjawanku 2024/2025 ↗The EPF Retirement Income Adequacy Framework sets its Adequate Savings level at RM650,000.
EPF, Retirement Income Adequacy Framework ↗As of October 2024, about 36% of active EPF members in the formal sector met the age-based Basic Savings level in place at the time.
EPF, December 2024 ↗More than 115,000 members used i-Lindung Phase 2 to extend life or critical illness protection to immediate family members in 2024.
EPF Annual Report 2024 ↗START WITH WHERE YOU ARE TODAY
Starting work, raising a family or buying a home? Let's understand your situation before looking at plans.
Ask Faizal
New to takaful? Let's start with your commitments and budget.
Does someone depend on your income? Let's talk about the support they may need.
Plan ahead for your family's healthcare and your children's education.
Review your outstanding home financing and any cover you already have.
WHAT WOULD YOU LIKE TO PREPARE FOR?
Choose the concern that's on your mind. Not sure where to start? You can ask Faizal first.
8solutions to explore
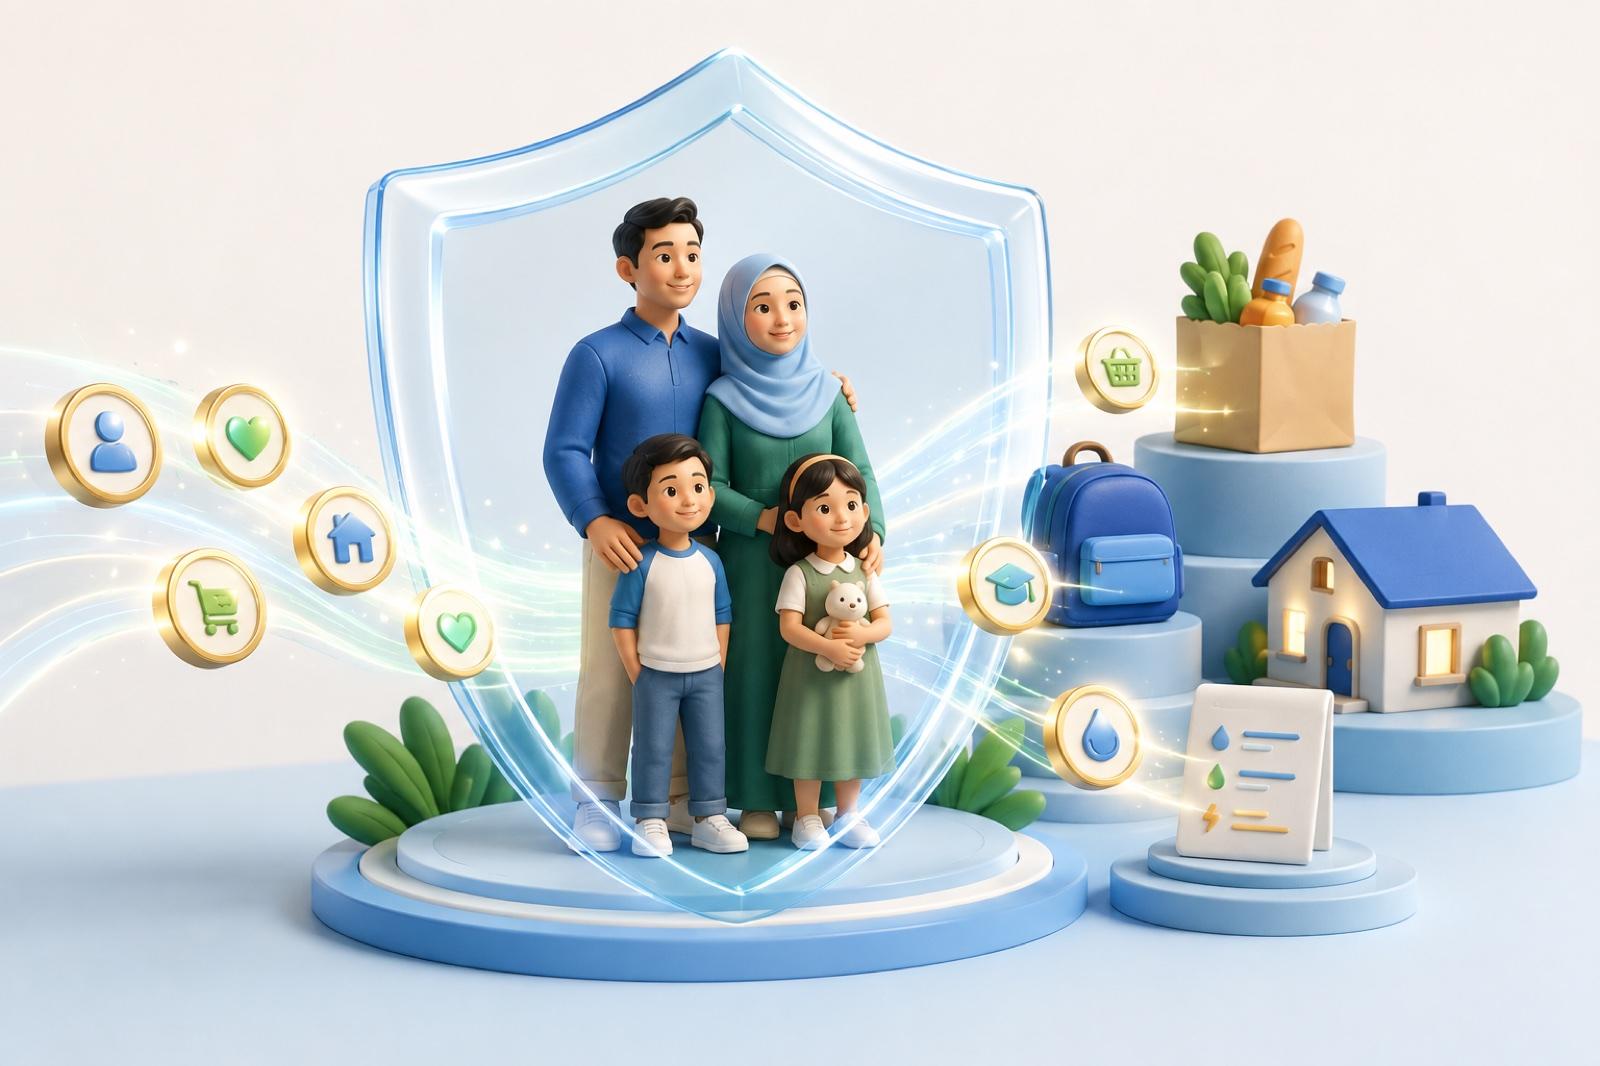
If a covered event stops your income, your family's bills still need paying. Let's talk about a fund that could help them manage.
“Your income may stop. Your family's needs don't.”
If a main earner dies or experiences a covered disability, groceries, rent, school fees and monthly bills still need paying.
Get help with eligible hospital bills. Let's also check the limits and what you may still need to pay yourself.
“When you're in hospital, it helps to know where you stand with the bill.”
A hospital bill can arrive unexpectedly. Cover from your employer may have limits, exclude certain treatments or end when you leave your job.
Hospital bills are one thing. Household bills while you recover are another. This cover may provide cash if a diagnosis meets the plan's terms.
“While you recover, the household bills keep coming.”
A medical card may help with eligible hospital bills. Home instalments, food, childcare and lost income during recovery still need planning for.
Explore a fund that could reduce or settle selected debts if a covered event happens.
“It's worth planning for the commitments your family may have to manage.”
Outstanding personal financing, car financing and other debts may still affect the estate and family if the breadwinner dies or becomes disabled.
Review the cover for your outstanding home financing so you know what support may be available if a covered event happens.
“A family home also comes with instalments worth planning for.”
If a borrower dies or becomes totally and permanently disabled, their partner may have to keep paying the home instalments on one income.
Your salary may stop, but the bills won't. Let's look at your retirement savings goal and what you already have.
“When your salary stops, what will cover your monthly spending?”
Food, housing, healthcare and day-to-day spending continue after retirement. Inflation may also push these costs up.
Children grow up quickly, and education needs planning too. Let's set a savings goal based on your child's age and your budget.
“When your child is ready for university, will the fund be ready too?”
Tuition, accommodation and living costs can be harder to manage if saving only starts when a child is about to enter college or university.
What are you saving for, how much do you need and when? Let's start with a clear goal and an amount you can keep putting aside.
“Give your goal an amount and a date. Then work out the steps.”
Savings can get spent on other things when there's no clear goal, contribution schedule or separate account for it.
These are general planning principles. The examples are fictional and help explain the ideas; they do not predict outcomes or promise payouts. Actual cover depends on the product, certificate terms, covered event and eligibility assessment.
SIMPLE BUDGET CALCULATOR
Adjust your age and budget to get a rough picture of the commitment. This simple calculation isn't a quote or confirmation of eligibility.
TRY THE NUMBERS
Choose an amount you feel you could keep paying. This figure doesn't tell you what benefits you would receive.
Want to understand your cover but not sure where to start? Tell me what you’d like to know. We’ll start with your questions, then discuss the information needed to understand the options relevant to you.
“You don't need to know every takaful term to ask a question. Let's take it one step at a time.”Faizal AhmadTakaful Consultant
COMMON QUESTIONS
These answers are a general guide. For your own plan, we need to check the details and certificate terms.
The process depends on the hospital, panel arrangements, guarantee letter and certificate terms. If circumstances allow, contact your operator or consultant beforehand.
That depends on the product, your age, health, underwriting and current terms. Review your existing cover before making changes.
Not always. Every certificate has its own benefit definitions, exclusions, waiting periods, limits and claim conditions.
Start with your family's spending, debts, dependants and existing cover. Then consider how long support may be needed and a budget you can keep paying.
START WITH ONE MESSAGE
Fill in the details below to prepare a WhatsApp message to Faizal. You can review it before sending. No payment or purchase takes place here.